• Products
  • Insights
  • Practice Management
  • Resources
  • About Us

Social Security Card

Think Remarriage Ends Benefits Tied to a Former Spouse? Think Again.

Carol had been remarried for years when she finally started collecting her Social Security. She felt good about the decision. Then, over coffee, a friend leaned in and said, “You know you could be getting a lot more, right?”

Carol had no idea what she meant. It turns out her marital history, including a marriage that ended decades ago, may have opened up claiming options she never knew existed.

Stories like Carol’s are more common than you’d think. With more adults divorcing and remarrying later in life, your marriage and divorce history can shape your Social Security benefits in ways that are easy to miss. Knowing the rules could mean a meaningfully bigger monthly check.


First, Social Security Rules You Should Know

As with anything Social Security-related, eligibility and claiming strategies can be nuanced. If you’ve been remarried and are looking to maximize your benefits, here are some key rules to keep in mind:

  • The 10-Year Rule
    One of the most important Social Security rules for divorced individuals involves the length of marriage.

    To qualify for benefits based on a former spouse’s earnings record, the marriage generally must have lasted at least 10 years, whether you’ve been married once or multiple times.

  • Remarriage Can Affect the Benefits of a Divorced-Spouse
    If you’re remarried, you generally cannot collect a divorced-spouse benefit based on a living former spouse’s earnings record while your current marriage is in effect.

  • The Age-60 Rule
    A person who remarries at age 60 or later may remain eligible for survivor benefits based on a deceased former spouse’s record.

  • Survivor Benefits Follow Different Rules
    The rules for survivor benefits are more flexible than the rules for divorced-spouse benefits.

    If a current or former spouse dies, you may be eligible for benefits based on their earnings record. In some cases, that benefit may be larger than the benefit you receive based on your own work history.

  • If a Later Marriage Ends, New Options May Become Available
    If a second or subsequent marriage ends because of divorce, death, or annulment, benefits connected to an earlier spouse may become available again if all eligibility requirements are met.

  • Multiple Marriages May Create Multiple Opportunities
    If you’ve had more than one marriage lasting at least 10 years, you may potentially have benefits tied to more than one former spouse’s record. Understanding all available options can be an important part of retirement-income planning.


Second, How the Rules Apply in Real Life

Here are four hypothetical scenarios showing how remarriage could affect someone’s Social Security benefits.

Note: All examples use hypothetical numbers.
Social Security Card

Think Remarriage Ends Benefits Tied to a Former Spouse? Think Again.

SCENARIO 1:

Your Former Spouse Passes Away After You’ve Remarried

Susan’s Timeline:

ring

Married 15 years

Broken Heart

Divorced

ring

Remarried at 62

check

Starts collecting her own Social Security benefit at 67

death symbol

Former spouse dies after delaying benefits until age 70

Susan was married to her former spouse 15 years before divorcing and remarrying at age 62. Because the marriage lasted more than 10 years and she remarried after age 60, Social Security rules generally allow her to remain eligible for survivor benefits based on her deceased former spouse’s earnings record.

When her former spouse dies, Susan may be able to switch from her own $2,000 monthly benefit to a larger survivor benefit of $3,600. Because she may also qualify for a spousal benefit based on her current husband’s record, she has three potential benefit amounts to compare. These benefits would not be added together. In this example, the $3,600 survivor benefit is the highest amount available to her.

Susan’s Social Security Benefit Options1

Monthly Income

Her own retirement benefit, claimed at age 67

$2,000

Survivor benefit based on her first spouse’s record

$3,600

Spousal benefit based on her second spouse’s record

$1,000

These amounts are shown for comparison and are not added together. Susan would generally receive the highest benefit available to her, which in this example is the $3,600 survivor benefit.


SCENARIO 2:

What Happens if a Remarriage Ends?

Mary’s Timeline:

ring

Married 12 years

Broken Heart

Divorced

ring

Remarried at 58

check

Starts collecting her own Social Security benefit at 67

death symbol

First former spouse dies

Mary was married to her first husband for 12 years before divorcing and remarrying at age 58. Because she remarried before age 60, she would generally be unable to collect survivor benefits based on her first husband’s record while her second marriage remained in effect.

After that marriage ended in divorce and her first husband later died, Mary may have become eligible for a larger survivor benefit based on his earnings record. In this example, she could switch from her $1,900 retirement benefit to the $3,200 survivor benefit.

Susan’s Social Security Benefit Options1

Monthly Income

Her own retirement benefit, claimed at age 67

$1,900

Survivor benefit based on her first spouse’s record

$3,200

These amounts are shown for comparison and are not added together. Mary would generally receive the highest benefit available to her, which in this example is the $3,200 survivor benefit.


SCENARIO 3:

What If You've Had More Than One Former Spouse?

James’s Timeline:

ring

Married 12 years

Broken Heart

Divorced

ring

Remarried for 11 years at age 61

Broken Heart

Second marriage ends in divorce

check

Starts collecting his own Social Security benefit at 67

death symbol

Both former spouses die

James was married twice, and each marriage lasted longer than 10 years before ending in divorce. After both former spouses die, he may be eligible for survivor benefits based on either spouse’s earnings record. In this example, he could switch from his $2,100 retirement benefit to the larger survivor benefit of $3,400.

James’s Social Security Benefit Options1

Monthly Income

His own retirement benefit, claimed at age 67

$2,100

Survivor benefit based on her first spouse’s record

$2,900

Survivor benefit based on her second spouse’s record

$3,400

These amounts are shown for comparison and are not added together. Jessica would generally receive the highest benefit available to her, which in this example is the $3,400 survivor benefit.


SCENARIO 4:

When You Claim Each Benefit Can Make a Big Difference

Olivia's Timeline:

ring

Married 15 years

Broken Heart

Divorced

ring

Former spouse dies

Broken Heart

Remarried at 62

check

Claims her own reduced retirement benefit at 62

death symbol

Contacts Social Security and applies to switch to the full survivor benefit at 67

Olivia was married to her former spouse for 15 years before divorcing. After her former spouse died, Olivia remarried at age 62. Because she remarried after age 60, she generally remains eligible for survivor benefits based on her former spouse’s record. At 62, she has not yet filed for Social Security.

Rather than claim a reduced survivor benefit immediately, Olivia claims her own reduced retirement benefit at age 62. By waiting to claim the survivor benefit, she avoids locking in an early-filing reduction. As she approaches 67, Olivia contacts Social Security to confirm her options and apply to switch to the full survivor benefit.

Olivia’s Age

Benefit She May Receive1

Monthly Income

62

Her own reduced retirement benefit

$1,400

67

Full survivor benefit based on her former spouse’s record

$3,200

These benefits are received at different times, not added together. As Olivia approaches 67, she should contact Social Security to confirm her eligibility and apply to switch to the survivor benefit.

Third, How Do You Find Out What You’re Entitled to?

Social Security may not automatically identify every benefit available through a former spouse’s record. If you believe you may qualify for a spousal or survivor benefit, contact the Social Security Administration and ask it to review your eligibility. Being prepared with information about your marital history can help make that conversation easier.

Before contacting Social Security, gather what you can:

  • Social Security numbers for yourself and any current or former spouses, if available
  • Marriage certificate(s)
  • Divorce decree(s)
  • Death certificate(s), if applicable

If you’re eligible for benefits based on a current or former spouse’s record, they can tell you how much that benefit would be, and whether it’s larger than what you’re currently receiving.

You generally don’t need to contact a former spouse to explore your eligibility. Social Security can tell you what information or documentation it needs to review benefits connected to that person’s record.

The Bottom Line: You May Have More Options Than You Realize

Like Carol, many people assume their Social Security benefit is set the moment they begin collecting. But marriage, divorce, remarriage, and the death of a current or former spouse can create options years or even decades later. You don’t need a complicated marital history to have more than one path available. You just need to know which questions to ask.


Appendix: How Claiming Age Affects Survivor Benefits

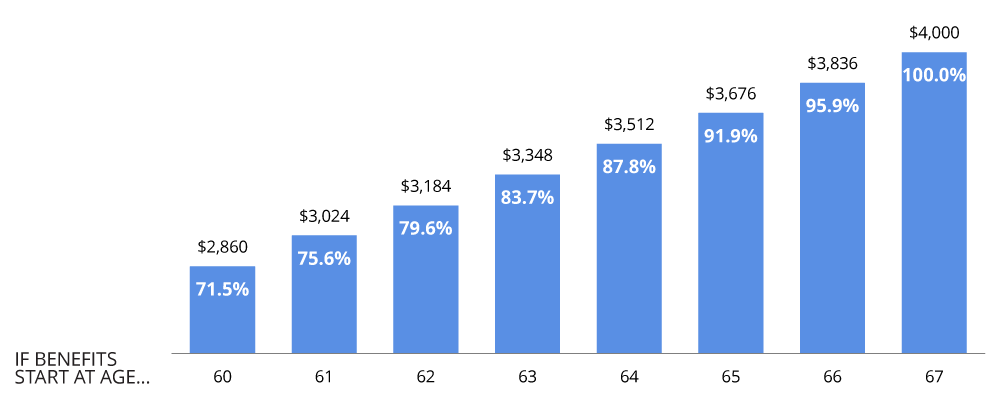
Survivor benefits may begin as early as age 60, but claiming before survivor-full-retirement age permanently reduces the monthly amount. The following illustration shows how the amount changes based on claiming age.

Portion that would be received assuming survivor benefit of $4,000 at a Full Retirement Age (FRA) of 672 

Note: Survivor benefits have their own FRA schedule, which is slightly different from the individual FRA. Benefits are subject to the earnings test and will be reduced if the survivor is still working and receiving earned income.


Next Step: 

Write down the names of each current or former spouse, along with the dates of each marriage and divorce. Then contact Social Security and ask whether another earnings record may provide a larger benefit or a different claiming option.


Author Headshot
Managing Director, Applied Insights

Mike educates financial professionals on a variety of topics, with a focus on research from the MIT AgeLab. Mike translates the knowledge of our various partnering experts—such as psychologists, physiologists, and practice-management specialists—into practical, actionable ideas for financial professionals and their clients.

Author Headshot

Curtis is a senior internal advisor consultant for Hartford Funds. He’s responsible for marketing Hartford Funds and The Hartford SMART529. He supports financial professionals and their clients with educational materials, product expertise, and practice-management strategies. He holds his National Social Security Advisor Certificate and is committed to educating professionals and their clients on social security-related topics.

1Illustrative examples only. Actual benefits depend on age, earnings history, marital history, claiming decisions, and Social Security eligibility requirements.

2What you could get from survivor benefits, ssa.gov, 2/26.  

All information provided is for informational and educational purposes only and is not intended to provide investment, tax, accounting or legal advice. 

As with all matters of an investment, tax, or legal nature, you should consult with a qualified tax or legal professional regarding your specific legal or tax situation, as applicable.

The MIT AgeLab is not an affiliate or subsidiary of Hartford Funds.

5984349

The material on this site is for informational and educational purposes only. The material should not be considered tax or legal advice and is not to be relied on as a forecast. The material is also not a recommendation or advice regarding any particular security, strategy or product. Hartford Funds does not represent that any products or strategies discussed are appropriate for any particular investor so investors should seek their own professional advice before investing. Hartford Funds does not serve as a fiduciary. Content is current as of the publication date or date indicated, and may be superseded by subsequent market and economic conditions.

Investing involves risk, including the possible loss of principal. Investors should carefully consider a fund's investment objectives, risks, charges and expenses. This and other important information is contained in the mutual fund, or ETF summary prospectus and/or prospectus, which can be obtained from a financial professional and should be read carefully before investing.

Mutual funds are distributed by Hartford Funds Distributors, LLC (HFD), Member FINRA|SIPC. ETFs are distributed by ALPS Distributors, Inc. (ALPS). Advisory services may be provided by Hartford Funds Management Company, LLC (HFMC) or its wholly owned subsidiary, Lattice Strategies LLC (Lattice). Certain funds are sub-advised by Wellington Management Company LLP and/or Schroder Investment Management North America Inc (SIMNA). Schroder Investment Management North America Ltd. (SIMNA Ltd) serves as a secondary sub-adviser to certain funds. HFMC, Lattice, Wellington Management, SIMNA, and SIMNA Ltd. are all SEC registered investment advisers. The funds and other products referred to on this Site may be offered and sold only to persons in the United States and its territories.

Hartford Funds refers to HFD, Lattice, and HFMC, which are currently not affiliated with any sub-adviser or ALPS.

On June 3, 2026, The Hartford Insurance Group, Inc. (“The Hartford”) and Wellington announced that they had reached a definitive agreement under which Wellington Investment Advisors Holdings, LLP, Wellington’s corporate parent, will acquire Hartford Funds. Upon closing Hartford Funds will be integrated into Wellington’s U.S. Wealth business. The deal is expected to close in the first quarter of 2027, subject to regulatory and fund approvals. Upon closing, Hartford Funds would become an affiliate of Wellington. For more information, click here.

© Copyright 2026 Hartford Funds Management Group, Inc. All Rights Reserved. Not FDIC Insured | No Bank Guarantee | May Lose Value