• Products
  • Insights
  • Practice Management
  • Resources
  • About Us

Much of what happens in Washington over the next two years will hinge on the 2026 midterms. Control of Congress is at stake, and the results will shape both President Donald Trump’s agenda and lawmakers’ legislative priorities. With several races becoming more competitive, exactly what that balance of power will look like remains unsettled.

Recent developments have generally moved in Democrats’ favor. They’ve gained ground in a number of House and Senate races, including some in traditionally Republican territory. Those shifts come against a challenging national backdrop for Republicans: Trump’s approval rating recently fell to 31%,1 while Democrats have maintained an advantage in generic congressional ballot polling.

But national trends only tell part of the story. Individual races, local dynamics, and voter turnout will ultimately determine whether Democrats’ recent gains translate into a shift in control

A broader path to a House majority doesn’t guarantee a Democratic wave.

A Competitive House Map Puts Control in Play

Democrats need a net gain of just three seats to take control of the House, and their opportunities have been expanding. Recent race ratings show Republicans defending competitive districts and open seats in traditionally Republican territory.

The movement isn’t limited to the usual battlegrounds, though. Several districts that backed Trump by double digits in 2024 have become more competitive, while a growing number of Republican-held open seats don’t have the advantage of an incumbent. That expands Democrats’ path to a House majority, but it doesn’t guarantee a blue wave. Republicans still benefit from the current congressional map, while candidate quality, local dynamics, and turnout could determine how far the pendulum swings.

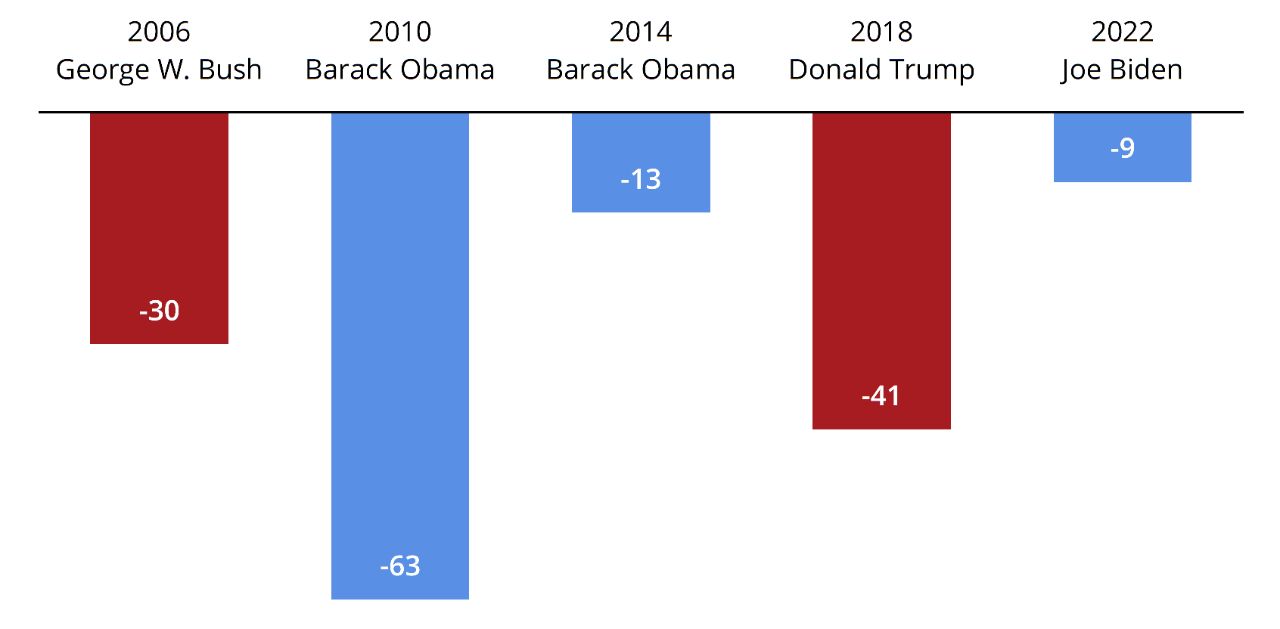
There’s plenty of historical precedent for significant midterm losses. Republicans lost 41 House seats under Trump in 2018, while Democrats lost 63 during President Barack Obama’s first midterm in 2010 (FIGURE 1). But the comparison only goes so far. Increased polarization and redistricting have made today’s House map less susceptible to dramatic swings, potentially putting a ceiling on Democratic gains even in a more favorable national environment.


FIGURE 1

Midterms Have Historically Cost the President’s Party House Seats
Net House Seat Change, 2006–2022

Source: The American Presidency Project, “Seats in Congress Gained/Lost by the President’s Party in MidTerm Elections,” 2026.


Several States Could Tip the Balance in the Senate

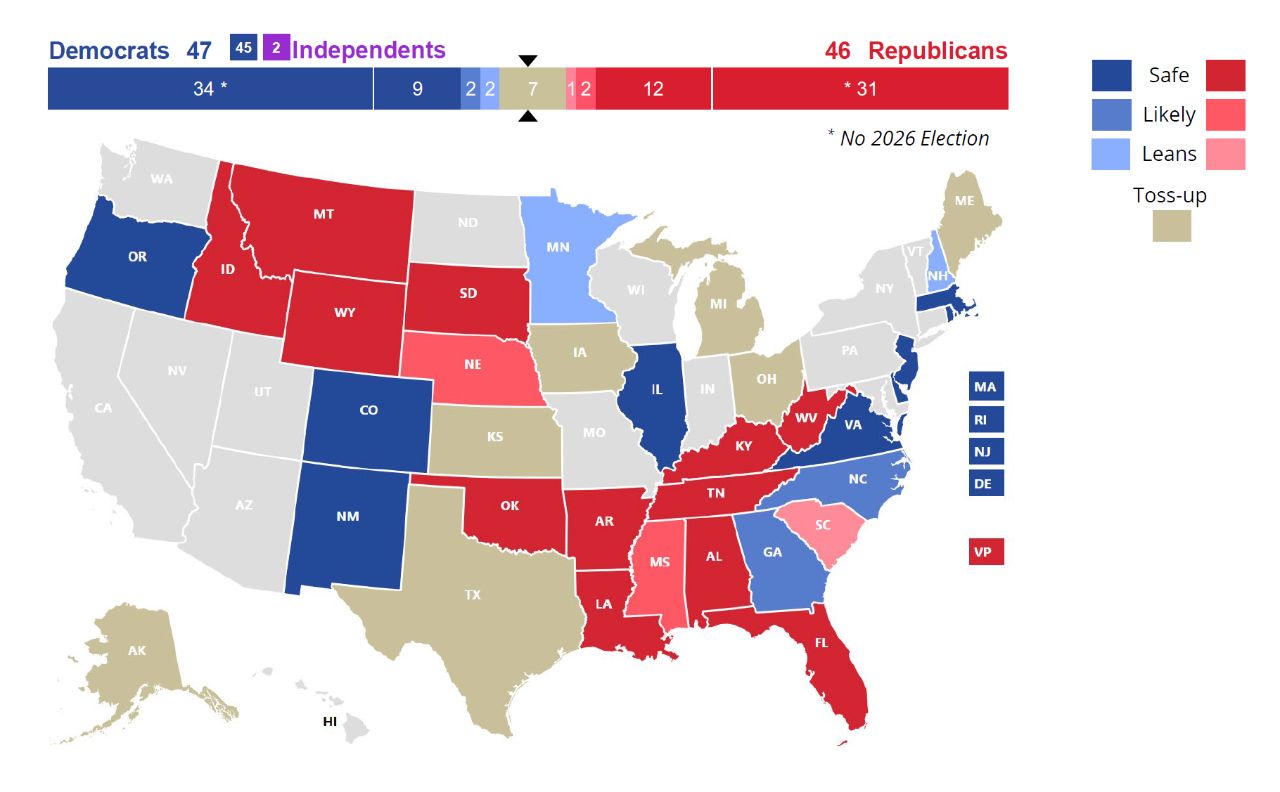
The fight for the Senate has also tightened. Republicans hold a 53–47 majority, leaving Democrats needing a net gain of four seats to take control. With competitive races stretching across an unusually broad map, the chamber is firmly in play.

Texas has emerged as one of the cycle’s most competitive and closely watched races, with Democrat James Talarico and Republican Ken Paxton essentially neck and neck. But Democrats’ opportunities extend beyond Texas. Alaska, Maine, and Ohio are among the states with tightly contested races, giving Democrats several potential pickup opportunities.

The broader map is also forcing Republicans to defend territory that would normally attract less attention. Races in states such as Kansas and Iowa have become increasingly competitive, while New Hampshire has moved toward Democrats. Even Mississippi has drawn additional Republican attention late in the race. Taken together, those developments suggest neither party can afford to focus solely on the traditional battlegrounds.

Democrats still have work to do to gain the four seats they need, and Republicans have a clear path to retaining control. But with more races in play, the battle for the Senate has expanded well beyond where it began.


FIGURE 2

A Competitive Map Keeps Senate Control Uncertain
2026 Senate Race

As of 10/23/26. Arrows above the map indicate the controlling party. In a 50-50 Senate, control is determined by the vice president (VP), who may cast tie-breaking votes. Source: Cook Political Report via 270toWin.

For Independent Voters, Turnout May Be the Bigger Question

Independent and unaffiliated voters are another group to watch closely as Election Day approaches. That’s particularly true given the growing share of Americans who don’t identify with either major party. If Democrats maintain their current advantage among these voters, it could have meaningful implications for the midterms.

Recent midterms show how much that margin can vary. Independents favored Democrats by 12 points in 2018, when Democrats gained 41 House seats, compared with just two points in 2022. But with a sizable share of independents still undecided, their impact on this year’s election remains difficult to predict.

The bigger question is whether these voters show up at all. In a Change Research poll conducted late this summer, just 58% of pure independents rated their motivation to vote at eight or higher on a 10-point scale, compared with 89% of Democrats and 82% of Republicans.2 More strikingly, 12% of Independents rated their motivation at zero, vs. just 2% of Democrats and 3% of Republicans. That turnout gap could ultimately matter as much as which party they favor.


What Changes After the Midterms, and What Doesn’t

Whatever the outcome of the midterms, the results will help shape the legislative and regulatory environment heading into 2027.

A shift in congressional control could redirect federal spending, regulatory oversight, and the legislative agenda, while new committee leadership could reshape negotiations around taxes, healthcare, financial regulation, and emerging technologies. A divided government, however, could make sweeping legislation more difficult, leaving executive action, agency rulemaking, and state policy to play a larger role.

The election could also usher in a sizable class of new lawmakers, bringing new priorities and potentially shifting the dynamics within both parties. A Democratic majority could put greater focus on affordability and congressional oversight, while continued Republican control of one or both chambers could bring a different set of legislative priorities and internal party considerations.

The election itself will mark a shift rather than an endpoint. Trade disputes, geopolitical conflicts, and other policy challenges will continue to shape the political landscape, even as the election resets the balance of power in Washington.
Talk to your financial professional to help make sure your portfolio is prepared for whatever happens in Washington, D.C. 

1 Reuters, “Trump’s Approval Falls to Record Low of 31% as Midterms Near, Reuters/Ipsos Poll Finds,” 10/20/26.

2 Source: FiftyPlusOne, “Independents Could Decide the Midterms, and They Aren’t Happy,” 8/14/26; Change Research poll conducted July 13–17, 2026.

The views and opinions expressed herein are those of the author, who is not affiliated with Hartford Funds. Hedgeye Potomac Research is not an affiliate or subsidiary of Hartford Funds.


POLWP039 6057885
About The Author
Author Headshot
Chief Political Strategist and Macro Policy Sector Head, Hedgeye Potomac Research

The material on this site is for informational and educational purposes only. The material should not be considered tax or legal advice and is not to be relied on as a forecast. The material is also not a recommendation or advice regarding any particular security, strategy or product. Hartford Funds does not represent that any products or strategies discussed are appropriate for any particular investor so investors should seek their own professional advice before investing. Hartford Funds does not serve as a fiduciary. Content is current as of the publication date or date indicated, and may be superseded by subsequent market and economic conditions.

Investing involves risk, including the possible loss of principal. Investors should carefully consider a fund's investment objectives, risks, charges and expenses. This and other important information is contained in the mutual fund, or ETF summary prospectus and/or prospectus, which can be obtained from a financial professional and should be read carefully before investing.

Mutual funds are distributed by Hartford Funds Distributors, LLC (HFD), Member FINRA|SIPC. ETFs are distributed by ALPS Distributors, Inc. (ALPS). Advisory services may be provided by Hartford Funds Management Company, LLC (HFMC) or its wholly owned subsidiary, Lattice Strategies LLC (Lattice). Certain funds are sub-advised by Wellington Management Company LLP and/or Schroder Investment Management North America Inc (SIMNA). Schroder Investment Management North America Ltd. (SIMNA Ltd) serves as a secondary sub-adviser to certain funds. HFMC, Lattice, Wellington Management, SIMNA, and SIMNA Ltd. are all SEC registered investment advisers. The funds and other products referred to on this Site may be offered and sold only to persons in the United States and its territories.

Hartford Funds refers to HFD, Lattice, and HFMC, which are currently not affiliated with any sub-adviser or ALPS.

On June 3, 2026, The Hartford Insurance Group, Inc. (“The Hartford”) and Wellington announced that they had reached a definitive agreement under which Wellington Investment Advisors Holdings, LLP, Wellington’s corporate parent, will acquire Hartford Funds. Upon closing Hartford Funds will be integrated into Wellington’s U.S. Wealth business. The deal is expected to close in the first quarter of 2027, subject to regulatory and fund approvals. Upon closing, Hartford Funds would become an affiliate of Wellington. For more information, click here.

© Copyright 2026 Hartford Funds Management Group, Inc. All Rights Reserved. Not FDIC Insured | No Bank Guarantee | May Lose Value